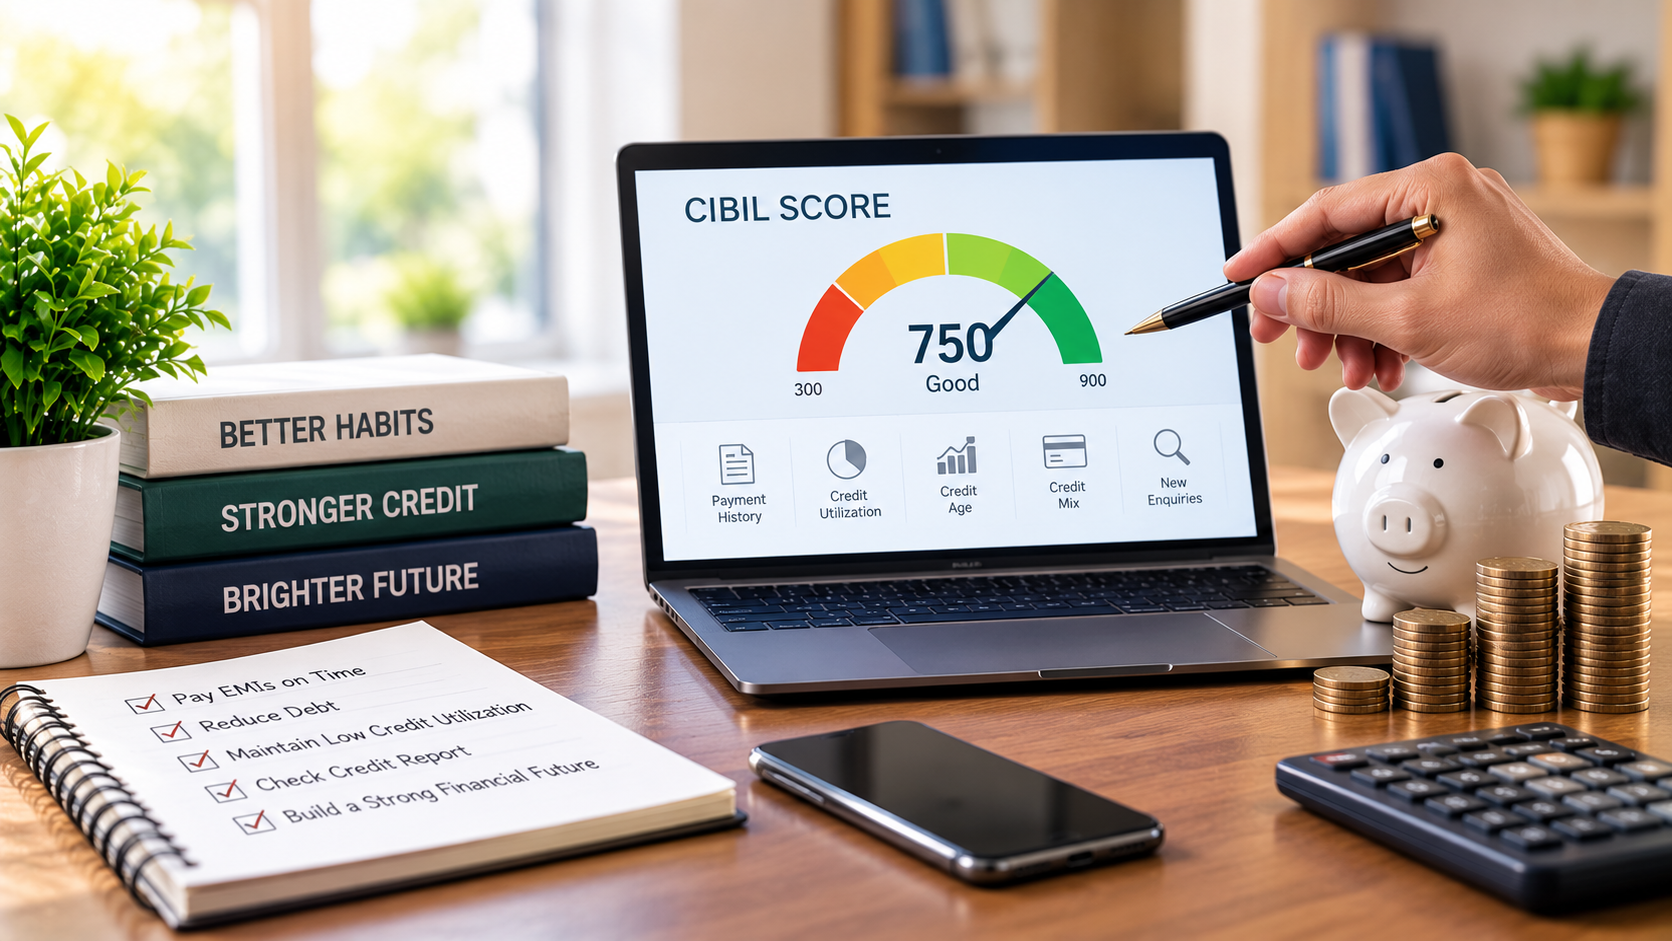
CIBIL Score After Vehicle Loan Settlement is an important concern for borrowers who have settled a car, commercial vehicle or other vehicle loan for less than the full outstanding amount.
When a lender accepts a negotiated amount instead of the complete amount originally payable, the loan account can be reported as “settled” rather than “closed”. TransUnion CIBIL explains that a settled status can be viewed negatively by lenders because it indicates that the borrower did not repay the complete amount originally due.
A vehicle loan settlement can therefore affect both your credit report and your ability to obtain new credit in the future.
What happens to your CIBIL after vehicle loan settlement?
A settlement doesn’t simply erase the vehicle loan from your credit history.
Your CIBIL Report contains information about loan accounts, payment history and account status. Automobile loans are specifically included among the credit facilities that can appear in the report.
When the lender accepts a settlement for less than the complete outstanding amount, the account can show a settled status.
This is different from a closed account.
A closed account generally indicates that the loan was fully repaid according to the lender’s records. A settled account indicates that the lender accepted a partial payment under an agreed settlement.
Does vehicle loan settlement reduce CIBIL Score?
The impact depends on your overall credit history and the information reported by lenders.
A settlement can have a negative effect on your credit profile because the account status and previous payment behaviour become part of your credit history. CIBIL states that written off, settled and suit filed accounts are not viewed favourably by lenders.
There isn’t a single fixed number of CIBIL points that every borrower will lose after vehicle loan settlement.
Your score is calculated using information in your credit report, including account and enquiry information.
This means the effect can differ from one borrower to another.
Settled vs closed vehicle loan
Understanding this difference is important.
Settled: The lender accepts an agreed amount that is lower than the total amount originally payable.
Closed: The loan has been fully repaid and the lender reports the account as closed.
CIBIL’s own example explains that when the complete amount was not repaid and the lender accepted a lower settlement amount, the account was reported as “settled”. When the complete payment was made, the account could instead be reported as “closed”.
For someone planning to apply for another vehicle loan, this distinction can matter.
Can you change a vehicle loan status from settled to closed?
In some circumstances, yes.
If you later pay the remaining amount that was not covered by the settlement and the lender agrees to update the account, the lender can provide confirmation and the credit bureau can update the reported status.
CIBIL describes a case where a borrower paid the remaining outstanding amount after settlement, obtained an NOC from the lender and raised a dispute. The account was subsequently changed from “settled” to “closed” after confirmation from the lender.
This isn’t an automatic process. The lender needs to update or confirm the relevant information.
How to improve CIBIL after vehicle loan settlement
Improving your credit profile takes consistent repayment behaviour over time.
1. Check your CIBIL Report
Start by checking the complete report rather than looking only at the score.
Review the vehicle loan account, payment history, outstanding balance and account status.
CIBIL provides access to a free CIBIL Score and Report once each calendar year.
2. Check whether the information is accurate
Look for incorrect information such as:
- Wrong outstanding balance
- Incorrect payment history
- Incorrect account status
- Duplicate loan account
- Incorrect dates
- Payments that haven’t been updated
CIBIL states that information in the report is supplied by banks and financial institutions, while CIBIL maintains and displays the information it receives.
3. Keep every future EMI payment on time
If you have other active loans or credit cards, pay the dues on time.
Your future payment behaviour becomes part of your ongoing credit history. A pattern of timely payments can help establish a stronger credit profile over time.
4. Avoid unnecessary loan applications
Applying for several loans within a short period can create multiple credit enquiries.
CIBIL records enquiries made by lenders when you apply for credit.
Apply only when you have a genuine requirement and a reasonable chance of meeting the lender’s eligibility requirements.
5. Keep existing debt manageable
After a vehicle loan settlement, taking on several new loans may create additional repayment pressure.
Focus on keeping your existing obligations under control and maintaining timely payments.
Can you get another vehicle loan after settlement?
You can apply for another vehicle loan after a previous settlement, but approval isn’t guaranteed.
Lenders generally review your CIBIL Score and Report along with income, existing repayment obligations and other information during the credit assessment process. CIBIL notes that lenders use credit history and score when evaluating loan applications.
A settled vehicle loan can therefore become one factor in a lender’s decision.
If you’re planning another vehicle purchase, review your credit report before applying.
How long does it take for settlement information to update?
Credit information isn’t necessarily updated immediately after you make a payment.
CIBIL states that banks and financial institutions typically report recent updates and payments to CIBIL, and updates may take around 15 to 30 days to appear.
If your lender has confirmed that the account information was updated but the report still shows incorrect information after the relevant reporting period, you can raise a dispute with CIBIL.
What if the settled status is incorrect?
If you believe the lender has reported incorrect information, first contact the lender and ask for clarification.
Keep documents such as:
- Settlement letter
- Payment receipts
- Bank statements
- NOC or lender confirmation
- Loan account statement
- Correspondence with the lender
If the lender confirms that the information submitted to CIBIL should be changed, the updated information can then be reflected in the credit report.
CIBIL provides a dispute process for consumers who identify incorrect information in their reports.
Can a vehicle loan settlement be removed from CIBIL?
CIBIL doesn’t independently delete accurate information simply because a borrower requests its removal.
CIBIL states that it collects credit information supplied by banks and financial institutions and cannot independently change or delete records reported by them.
If the settlement information is accurate, it should not be treated as an incorrect entry.
If the account has later been fully resolved and the lender agrees to update its status, the lender’s revised reporting can lead to a change in the credit report.
What should you do after vehicle loan settlement?
After completing a vehicle loan settlement, keep your documents safely and monitor your credit report.
You should:
- Obtain written confirmation from the lender
- Keep proof of the settlement payment
- Check the vehicle loan account on your CIBIL Report
- Verify the reported account status
- Check for incorrect outstanding amounts
- Continue paying other loans and cards on time
- Avoid unnecessary credit applications
- Raise a dispute if the reported information is incorrect
If you need to discuss your loan settlement situation, you can also contact the Settlement on Loan team.
FAQs about CIBIL after vehicle loan settlement
Does vehicle loan settlement affect CIBIL?
Yes. A settled vehicle loan can negatively affect your credit profile because the account may be reported as settled rather than closed.
How many points does CIBIL decrease after vehicle loan settlement?
There is no fixed number of points that applies to every borrower. The impact depends on the information in your overall credit history.
Can I improve my CIBIL after vehicle loan settlement?
Yes. Continue making payments on time, keep your credit obligations manageable, avoid unnecessary applications and check your credit report regularly.
Can settled status become closed?
It may be possible if the remaining amount is subsequently paid and the lender agrees to update the account. CIBIL documents a case where such a status change occurred after the remaining amount was paid and the lender confirmed the update.
Can I get a new car loan after settlement?
You can apply, but the lender will make its own credit assessment. Your settled vehicle loan can be considered along with your score, repayment history, income and other financial information.
How can I check whether my vehicle loan settlement is updated?
Check the account section of your latest CIBIL Report. Review the account status, current balance, overdue amount and payment history.
Final thoughts
CIBIL Score After Vehicle Loan Settlement can be affected because a settlement may be reported as “settled” instead of “closed”. This status can influence how lenders view a future credit application.
After settlement, check your CIBIL Report carefully and make sure the information reported by the lender is accurate. Continue paying all other credit obligations on time and avoid unnecessary borrowing.
If the lender later agrees to update the account after the remaining amount has been paid, keep the lender’s confirmation and check that the revised information appears correctly in your credit report.