Indian family receiving loan settlement and debt repayment guidance
Loan Settlement Support in India

Helping You Manage Your Loan Burden With Clarity.

Struggling with multiple EMIs, overdue loans or financial hardship? Settlement On Loan helps borrowers understand available options, prepare their case and communicate with banks or NBFCs before making an important financial decision.

₹ Loan Settlement Support
↓ Repayment Options
✓ Written Terms Review
↔ Bank & NBFC Guidance
Start With Clarity Understand your current debt position before deciding your next step.
👥
15K+ Cases Assisted
₹
Free Initial Consultation
★
4.9/5 Customer Rating
✓
1-on-1 Case Guidance
ⓘ Important: Settlement is subject to lender approval and individual account circumstances. Paying less than the full contractual dues may affect how the account is reported to credit bureaus.
What We Do

Support that feels clear, human and manageable.

Every debt situation is different. Explore the services below and use Quick Look to understand what each service covers before opening a detailed page.

Service 01 Personal loan settlement support

Personal Loan Settlement

Review unsecured personal-loan hardship, lender communication and possible settlement paths.
Know More
Service 02 Credit card settlement support

Credit Card Settlement

Understand card dues, repayment alternatives, written settlement terms and credit implications.
Know More
Service 03 Business loan settlement support

Business Loan Settlement

Assessment support for business debt, lender OTS discussions and financial hardship.

Know More
Service 04 Debt closure guidance

Debt Closure Guidance

Understand payment completion, settlement documentation, NOC and account status.

Know More
Service 05 Recovery communication support

Recovery Communication Support

Organize communication records and understand lender grievance or escalation pathways.
Know More
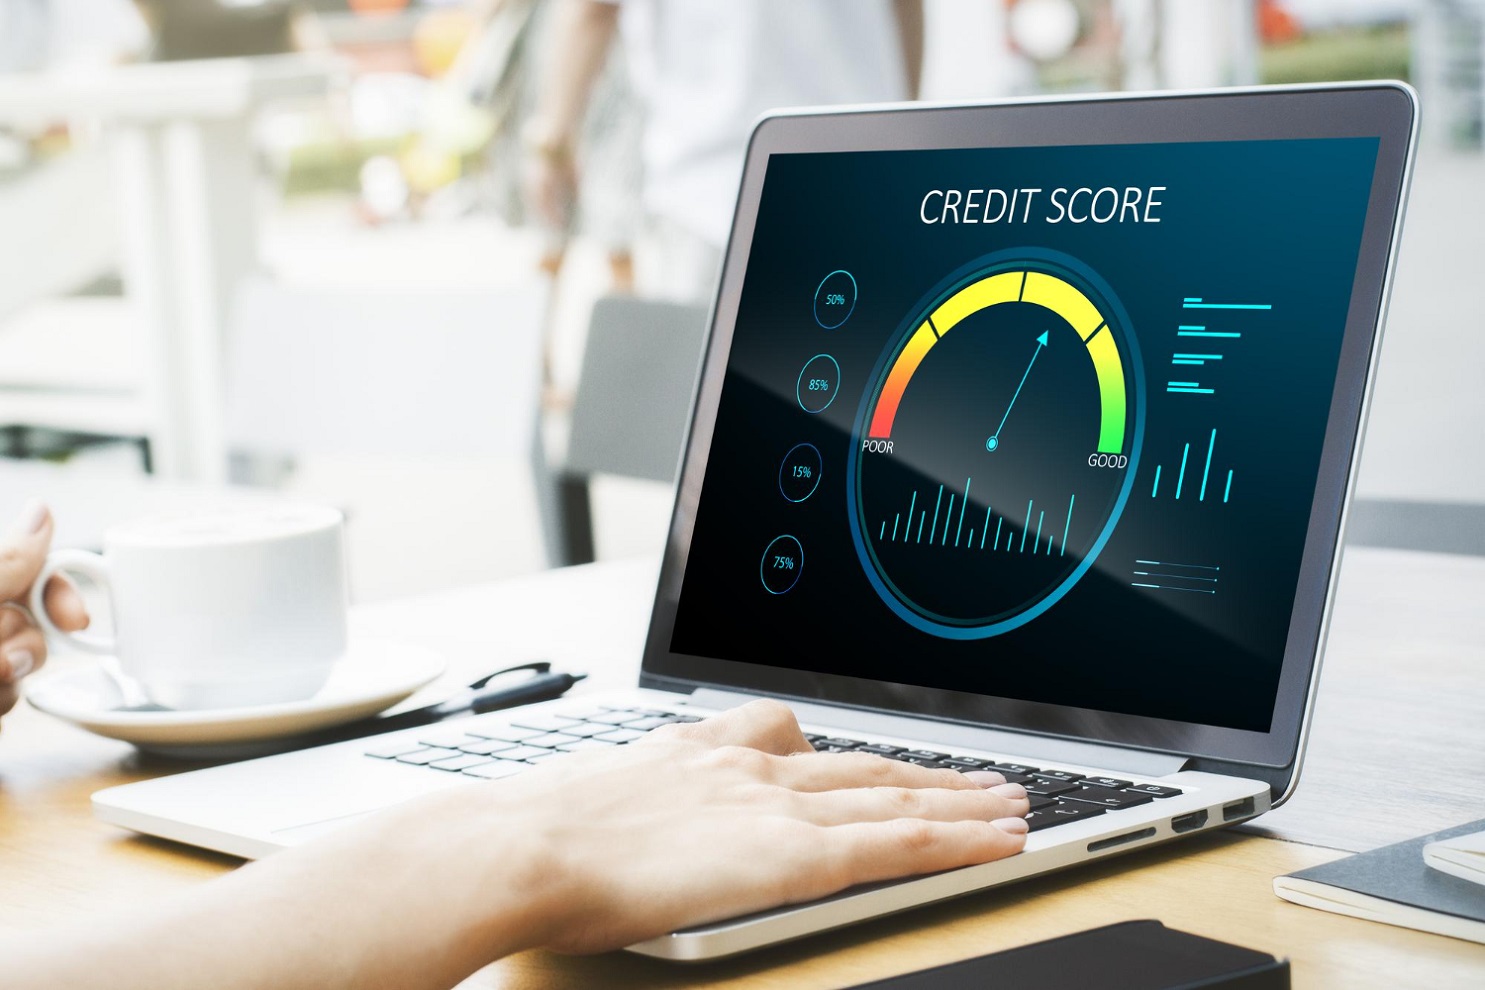
Service 06 Credit report guidance

Credit Report Guidance

Understand settled versus closed status, factual corrections and lender-reported information.
Know More
Transparent Pricing

Know the service fee before you proceed.

Adjust your outstanding debt to understand the Basic Plan service fee. This estimate is separate from any amount a lender may accept toward settlement.

Basic Plan

Simple fee structure with clear calculation.

The Basic Plan combines a one-time sign-up fee with a monthly service fee calculated according to the total outstanding debt.

One-time sign-up ₹1,000 + GST
Monthly service fee ₹1,000 / ₹1 lakh
Basic Plan duration 5 Months
Note: Premium Service pricing may differ. This calculator represents SOL service fees only, not a guaranteed lender settlement amount.
Interactive Estimate

What is your total outstanding debt?

Move the slider or choose a quick amount to calculate the estimated Basic Plan service fee.

GST Extra
Outstanding debt ₹5,00,000
₹1L ₹25L ₹50L
Sign-up fee ₹1,000
Monthly service fee ₹5,000
Five months service fee ₹25,000
Basic Plan total before GST ₹26,000 GST is additional.
₹
Calm Guidance Borrowers reviewing household finances
You do not need to solve everything in one day. Start by understanding where your account stands and which options are genuinely available before taking the next step.
A Simpler Process

One step at a time, without the pressure.

The process begins with understanding your situation. A settlement proposal is considered only after reviewing the lender, repayment stage, hardship, documentation and available alternatives.

01
Understand your current position

Review lender, outstanding balance, overdue status and current repayment ability.

02
Understand the hardship

Income disruption, medical costs, business slowdown or other genuine circumstances are reviewed.

03
Compare available paths

Normal repayment, revised arrangements, restructuring or lender-approved settlement may be discussed.

04
Review written terms

Verify amount, deadline, lender authorization and approved payment channel before payment.

05
Keep closure records

Maintain settlement letter, payment receipt and subsequent account-status documentation.

Important: Settlement outcomes depend on lender approval, account status and individual circumstances. Written terms should always be reviewed before making payment.
Before Deciding

Settlement may be one path. It is not the only path.

The right choice depends on your ability to repay, account status, lender policy and the alternatives still available to you. Before deciding, it is important to understand whether settlement is suitable for your situation or whether another repayment path may be better.

Worth Assessing
✓

When settlement may need review

✓ Regular EMIs have become genuinely unaffordable.
✓ The account is overdue or recovery communication has started.
✓ Financial hardship can be reasonably explained and documented.
✓ You understand the potential credit-report implications.
Also Consider
↗

Alternatives before settlement

→ Continue normal repayment if it is still manageable.
→ Ask the lender about revised payment arrangements.
→ Explore restructuring where the lender offers it.
→ Seek independent legal advice for secured debt or court matters.
Important: Settlement should be considered only after reviewing your repayment ability, lender policy, possible alternatives and credit-report impact.
Credit Reporting

Settled and closed are not automatically the same.

The repayment route and lender-reported status are important parts of the decision. Understanding the difference can help you avoid confusion before choosing a repayment or settlement path.

VS
Full Repayment
✓

Closed

Where the lender-required dues are fully paid, the lender may subsequently report the account as closed after internal processing and confirmation.

Usually linked with full payment The final status depends on lender records, processing time and bureau reporting.
Compromise Payment
↓

Settled

Where the lender accepts less than the contractual outstanding amount, the reporting outcome can differ from full repayment.

May differ from full closure Paying less than contractual dues may affect how the account is reported to credit bureaus.
Important: No fixed credit-score change, deletion or recovery period should be promised. Reporting depends on lender-confirmed facts and the credit bureau process.
Before Payment Loan settlement document and closure guidance
Do not pay without checking the written terms. A genuine settlement letter should clearly mention the lender, account, amount, deadline and approved payment route.
Before Making Payment

A settlement letter should reduce uncertainty.

Before paying an agreed settlement amount, understand exactly what the lender has approved, which account the payment relates to and whether the terms are documented clearly.

✓
Verify lender authorization

Make sure the communication is genuinely lender-approved and not only an informal message.

✓
Check account and amount

Confirm the exact loan account, settlement figure, deadline and payment conditions.

✓
Use the approved payment route

Do not rely on informal personal payment requests or unverified payment links.

✓
Understand account reporting

Settlement should not automatically be assumed to mean full closure or no credit-report impact.

✓
Keep proof after payment

Maintain the settlement letter, payment receipt and subsequent lender documentation.

Important: Settlement is subject to lender approval and individual account circumstances. Always verify written terms before payment.
Loan Settlement Assessment

Estimate Your Possible Loan Settlement

Select your lender and enter your current loan status. The calculator uses lender category, days past due and repayment tenure to show an indicative settlement range.

1
Select Lender
2
Enter Loan Status
3
View Estimate
Your Loan Details

Tell us about your current loan

Enter lender, outstanding amount, overdue days and repayment tenure to generate an indicative assessment.

Start typing lender name
Category -
Lender Type -
Current lender outstanding
₹
Days since payment became overdue
Used to calculate tenure ratio
Tenure paid ratio 0%
₹

Your estimate will appear here

Select a lender and enter your outstanding amount, DPD and repayment details to understand the settlement model applicable to your case.

Settlement Assessment

Lender

-

Assessment Ready
Estimated Planning Settlement Amount ₹0 -
Estimated Waiver -
Borrower Pays -
Possible Payable Range - Based on model band
Estimated Relief Range - Indicative only
Days Past Due -
Tenure Paid -
Matched Calculation Case -
Planning payable 50%
Estimated borrower payment Model-estimated waiver
Important: This is an indicative model estimate, not a lender-approved settlement offer.
Calculator note: This assessment uses lender category, DPD and EMI tenure ratio to generate an indicative waiver/payment range. Actual settlement, waiver, timing and approval remain subject to lender policy, account status, documentation, negotiation and borrower circumstances.

We are Here To Help!

Navigating the complexities of loan Settlement can be daunting. Personal Loan Settlement offers a beacon of hope, providing a strategic approach to manage and diminish your loan burdens.

Get Free Consultation

Complete the form below to get a call back.